When is the Best Time to Invest? Don’t Just Follow the Crowd
I love amusement parks.
I’m thankful to spend my summers close enough to Cedar Point to visit often.
I recently planned to go with my kids and a few of their friends. According to the forecast, we could pick a rainy Saturday or a Sunday without a cloud in the sky. At first glance, the sunny day looked like the obvious choice.

Most people don’t know how they’re doing financially
Most people don’t know how to know how they’re doing with money. Others don’t even want to know.
This free assessment is how to know.
If you’re brave enough to find out how financially strong you are, take it now!

Does Your Checking Account Check this Box?
As a personal finance coach, I worked with a couple who loved learning, reading, music, gardening, fitness, each other, and their two children.
They had been happily married for 8 years without learning much about personal finance. They hoped the professionals would pay attention to their financial details— while they focused on the more important things in life.
As I got to know the couple, I gradually shared personal finance insights with them. They began to turn more attention than ever toward their accounts.
Then they noticed something they had never seen before:

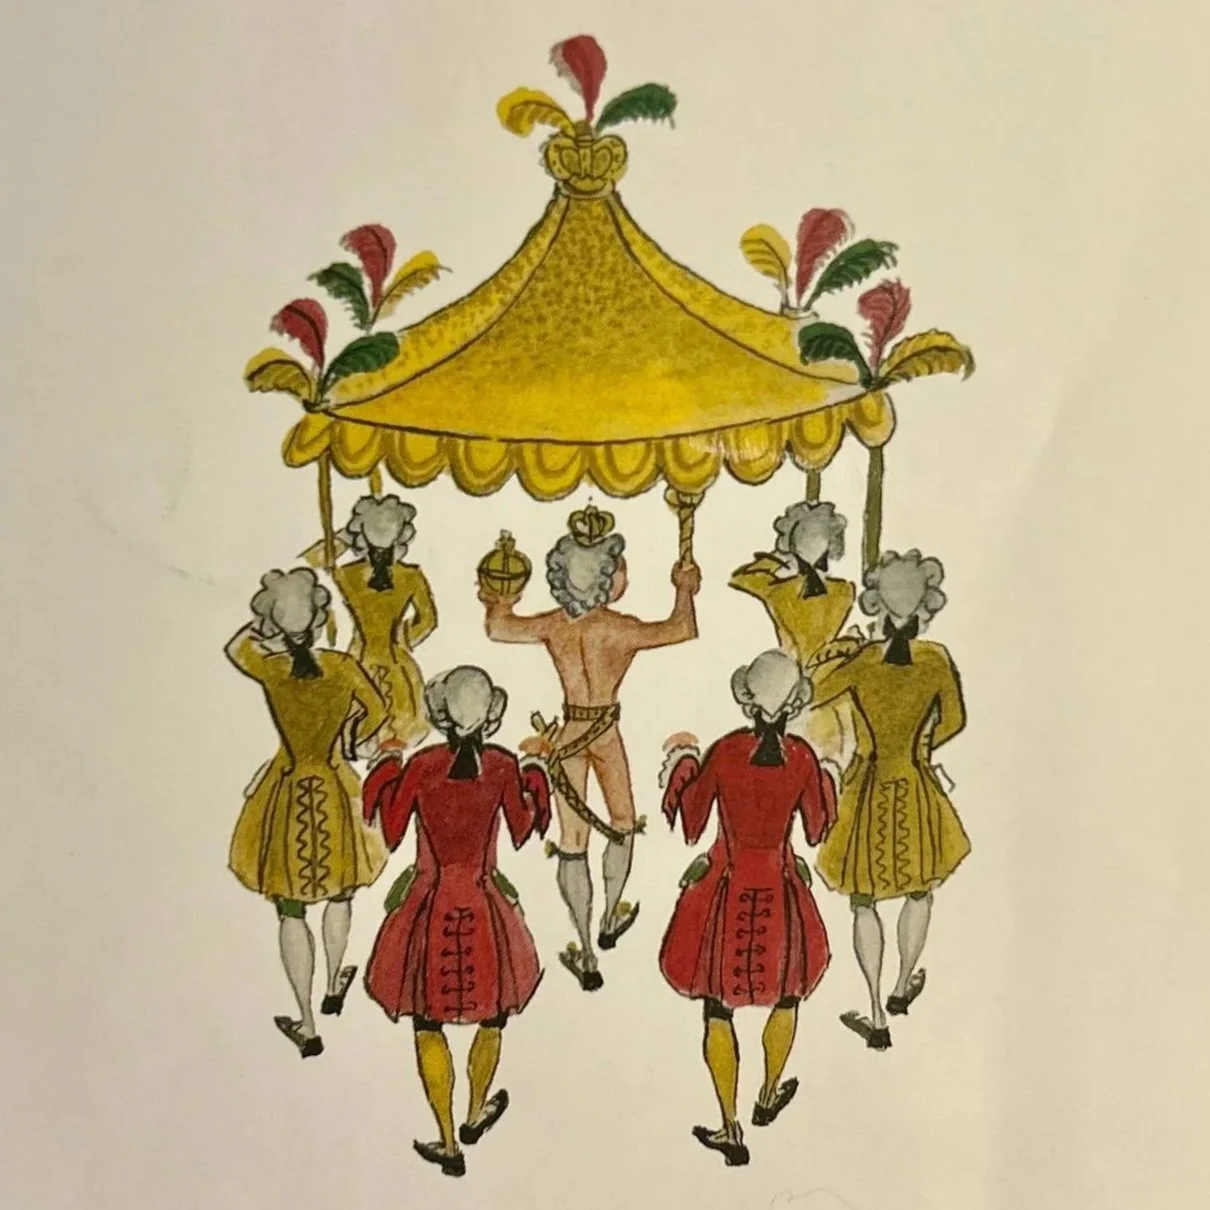
The Emperor’s New Clothes and the Courage to Spend Differently
Have you ever watched everyone around you buy something and wondered why?
Maybe it’s a kitchen renovation, a trendy travel mug, a sugary drink, or an overseas trip. Everyone else seems to love this stuff, so I guess you should, too.
But what if you don’t?

The Overlooked Key to Debt Payoff
Personal finance nerds debate endlessly about which tactics to use to pay off debt.
Should you prioritize building up your savings first— or keep your savings low while you throw as much as possible toward debt?
Should you focus on paying off your original loan— or switch loans to get a lower interest rate?
Should you refinance? Consolidate? Use a balance transfer?
There are good arguments to be made for many of these strategies. But sometimes we can become so focused on choosing the right tactic that we overlook the thing that matters most:
How fast are you actually paying off the debt?

The #1 Way to Secure Your Kids' Financial Future
One night when I was pushing 40 and my kids were young, I lay awake, unable to sleep.
I thought about how life is short. My kids love animals. For pet show-and-tell day at preschool, they took a roly poly from the garden (or as we call them, Armadillidiidae). Aside from that, they had never had a pet.
I worried: Are they really going to grow up without a pet? How do people afford pets?
In the couple of years that followed, these worries helped me realize something. The dreams my husband and I had for our kids wouldn’t happen simply because we wanted them to. They would become possible only if we grew our financial strength and confidence.

A Strong Marriage Is a Money-Strong Marriage
I've talked with spouses who say, "I'm not interested in that boring money stuff. That's what my partner is for. They enjoy it, and they do a great job."
Historically, I wasn't much of a money person. Somewhere in the back of my mind, I hoped my husband would somehow keep an eye on our finances—whatever that meant.
In hindsight, that wasn't fair to either of us. As long as I believed one person could handle the money, we were both missing out.

Why Does Buying My Next Car Feel So Hard?
In the winter of 2012, two weeks before our first child was born, I bought my uncle’s 2004 Toyota Sienna minivan for $7,500.
Over the years that followed, I prayed that it would keep running as long as possible. I wanted it to last forever.
For one thing, it was a practical car. But I also dreaded having to spend money on its replacement.

6 Free Financial Health Quizzes Worth Trying
How healthy are your finances?
You might immediately think of your income, credit score, debt balances, savings, or net worth. Those numbers matter, but your financial health is bigger than any single number. A few thoughtful questions can reveal where you stand and point you in the right direction.
I found six free financial health quizzes worth trying. Set aside a few minutes and take each one. Then ask yourself: What differences do you notice? What themes do they share in common? Which questions make you pause?

Can Budgeting Happen By Accident?
In the fall of 2011, I was, like Beyoncé, expecting my first child— a daughter.
I planned to stop working full-time after the baby was born. Even I could admit it was a good time to seek guidance about money, despite my distaste for the topic.
When my husband and I met with someone for money advice, the expert reviewed our spending.
He said, “You guys are fine. You basically practice intuitive budgeting.”
I interpreted this as validation of my avoid-numbers-and-stay-uninformed approach. “Intuitive budgeting” became my official excuse not to learn more.

Decluttering Your Stuff and Money: 5 Surprising Similarities
There's a feeling most of us know well.
You walk into a room piled with stuff you don't quite know what to do with, and you feel a pit in your stomach. A low hum of stress. A vague sense that you should deal with it, but you're not sure where to start. So you close the door.
There's another version of that feeling. You open your banking app, glance at your account balance, cringe a little, and close the app. You tell yourself you'll look at it more carefully later.
When what you own is in disarray, without a system to make sense of it, it doesn’t feel good.

8 Personal Finance Voices Worth Hearing
Who taught you what you know about money? Many of us had a key role model whose advice still echoes in our minds. Some of us floundered without anyone to teach us. Maybe you still wonder where to turn for guidance.
Whether or not anyone taught you about money in the past, it's important to get the right voices in your ear as you move forward. The personal finance world changes constantly. Your own life circumstances evolve. True money strength means keeping your curiosity alive and your awareness fresh.

All You Need to Know About Investing in 5 Definitions
Have you ever started to learn about investing, only to get lost in a sea of jargon? The technical terms make investing feel overwhelming. No wonder so many people lack confidence.
Here’s the truth: you don’t need to know everything to be a successful investor. In fact, you only need to understand a handful of simple terms. If you tune out the intimidating language and grasp the key concepts, you’ll know enough to invest wisely.

What is an Emergency Fund?
Life throws curveballs. A flat tire, a surprise medical bill, or an unexpected job loss can shake your financial stability. Without a safety net, these events don’t just disrupt your routine— they can push you into debt, stress, and panic.

Your Financial Life Is Bigger Than Spending
If you see your spending more than other areas of your financial health, you are at risk.
For years, spending was the only aspect of my financial life that I saw.
Everything changed when I stopped seeing spending as the whole story.
Spending is the loudest part of your financial life. It demands your attention almost every day. Groceries. Gas. Birthday gifts. Shoes. Shampoo. The Costco run that magically turns into $353 every time.

Tradeoffs Made Simple: How to Say Yes Without Regret
Have you ever felt so excited to buy something you wanted, only to question yourself and feel guilty later?
Maybe it was a dinner out, a new phone, a piece of furniture, or a weekend trip. In the moment, you said yes wholeheartedly. Afterward, you wondered if that “yes” meant saying no to something more important.
Here’s the thing: every money decision involves a tradeoff, whether we like it or not.
But the tradeoffs don’t have to feel confusing or painful. Awareness of tradeoffs isn’t just about saying no. This mindset can help you say yes with confidence.

Pay Down Your Mortgage or Invest? The Tradeoff Worth Understanding
You’ve built stability. You’re covering your expenses. You’re contributing for retirement. You’ve even knocked out your high-interest debt.
When you make it to this point, you’re not just solving problems anymore. You think proactively.
You have a different kind of question:
What should you do with the extra money?
Do you send it toward your mortgage—chipping away at a decades-long obligation? Or do you invest it, putting your money to work for future growth?
This is one of those personal finance debates that never subsides. Like most debates that stick around this long, it persists because both sides make compelling points.

There’s Only One Right Way to Pay Off Debt (And Everyone Agrees)
Spend enough time in personal finance circles and you’ll start to think there are dozens of competing philosophies about how to pay off debt. One expert insists you should attack the smallest balance first. Another says that’s mathematically foolish; you should focus on the highest interest rate. A third tells you neither approach matters if you’re not simultaneously investing.
It sounds like disagreement. It sounds like conflict.
But amidst the noise, there’s an overlooked truth: they all agree.
There's only one good way to pay off non-mortgage debt. And it’s the same framework every credible personal finance educator teaches— whether they frame it differently or not.

Financial Strength Isn’t Built Overnight; Here’s How to Keep Growing
If you’ve ever wished for a quick fix to your money challenges, you’re not alone.
It’s captivating to imagine a quick route to financial success.
But here’s the truth: financial strength isn’t built overnight. Just like building physical strength or growing a tree, it takes time, consistency, and steady progress.
The great news is you don’t need a miracle to succeed, but you do need to keep growing, one step at a time.

5 Questions To Reveal What Matters Most in Your Financial Life
Most people manage their money on autopilot. They don’t have a game plan. They pay the bills, spend on whatever comes up, and save what’s left over—if anything.
The problem: Without intentionality, money slips away on things that don’t matter, leaving you perpetually stressed and unfulfilled.
The great news: You might not need more money to feel more in control. You might just need clarity.
When you see clearly how money connects to what matters to you, you see the control panel of your finances. You’re no longer in the dark, making mindless and misinformed decisions.